Briefing Note
Following on from The Chancellor of the Exchequer’s Autumn Budget, we aim to provide a short briefing note confirming the pertinent points arising, specifically in relation to property.
High Value Council Tax Surcharge (Mansion Tax)
From April 2028, owners of properties identified as being valued at £2 million plus, by the Valuation Office Agency (VOA) in 2026, will be liable for a recurring annual charge which will be additional to existing council tax liability.
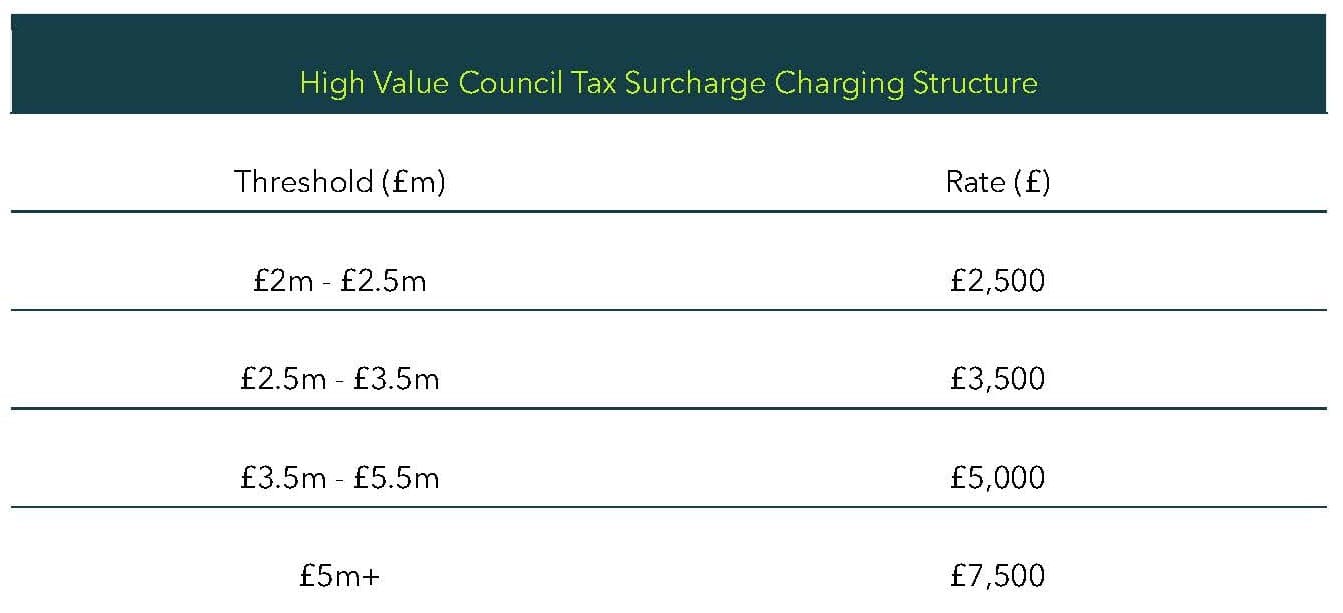
There will be four price bands with the surcharge rising from £2,500 for a property valued in the lowest £2 million to £2.5 million band, to £7,500 for a property valued in the highest band of £5 million or more, all uprated by CPI inflation each year.
The property values will not be based on the last point of purchase, but rather on new valuations to be carried out by the Valuation Office. This will reflect their value in 2026.
The government has announced a consultation on the measures, meaning not all details are confirmed. Details of where the other bands will land have not yet been shared, nor have details of any assumed deferral scheme. Previous reports had indicated homeowners would be able to defer the cost until they die or move house to avoid forcing them to sell up.
It has also not been revealed how the government will draw the line to decide which properties to revalue, however it has been floated that this will be done by looking at only the 2.4 million properties in the top three council tax bands (F, G and H) across the UK.
Income Tax (Landlords)
Landlords are now to pay an additional 2% on income tax, as higher levies were announced for property, savings, and dividend income. From April 2027, the basic, higher and additional rates of income tax on property and rental income will rise to 22%, 42% and 47%, respectively.
Business Rates
The Government have confirmed they will permanently lower business tax rates (Business Rates) for more than 750,000 retail, hospitality and leisure properties. This is to be funded through higher rates on properties with rateable values (RVs) above £500,000 such as warehouses or large industrial premises.
Capital Gains Tax (CGT)/Business Asset Disposal Relief (BADR)
Capital Gains Tax on Business Asset Disposal Relief rate rises from 14% to 18% from April 2026.
With the obstacle of the Budget now out of the way, and, with most of the pre-budget rumours not enforced, we hope it stimulates the property market immediately.
BCM Wilson Hill are on hand to assist you with your property following the outcome from the budget. If you would like to discuss this further, please contact anyone within our four offices across the South East.